New Venture Funds - October 2026
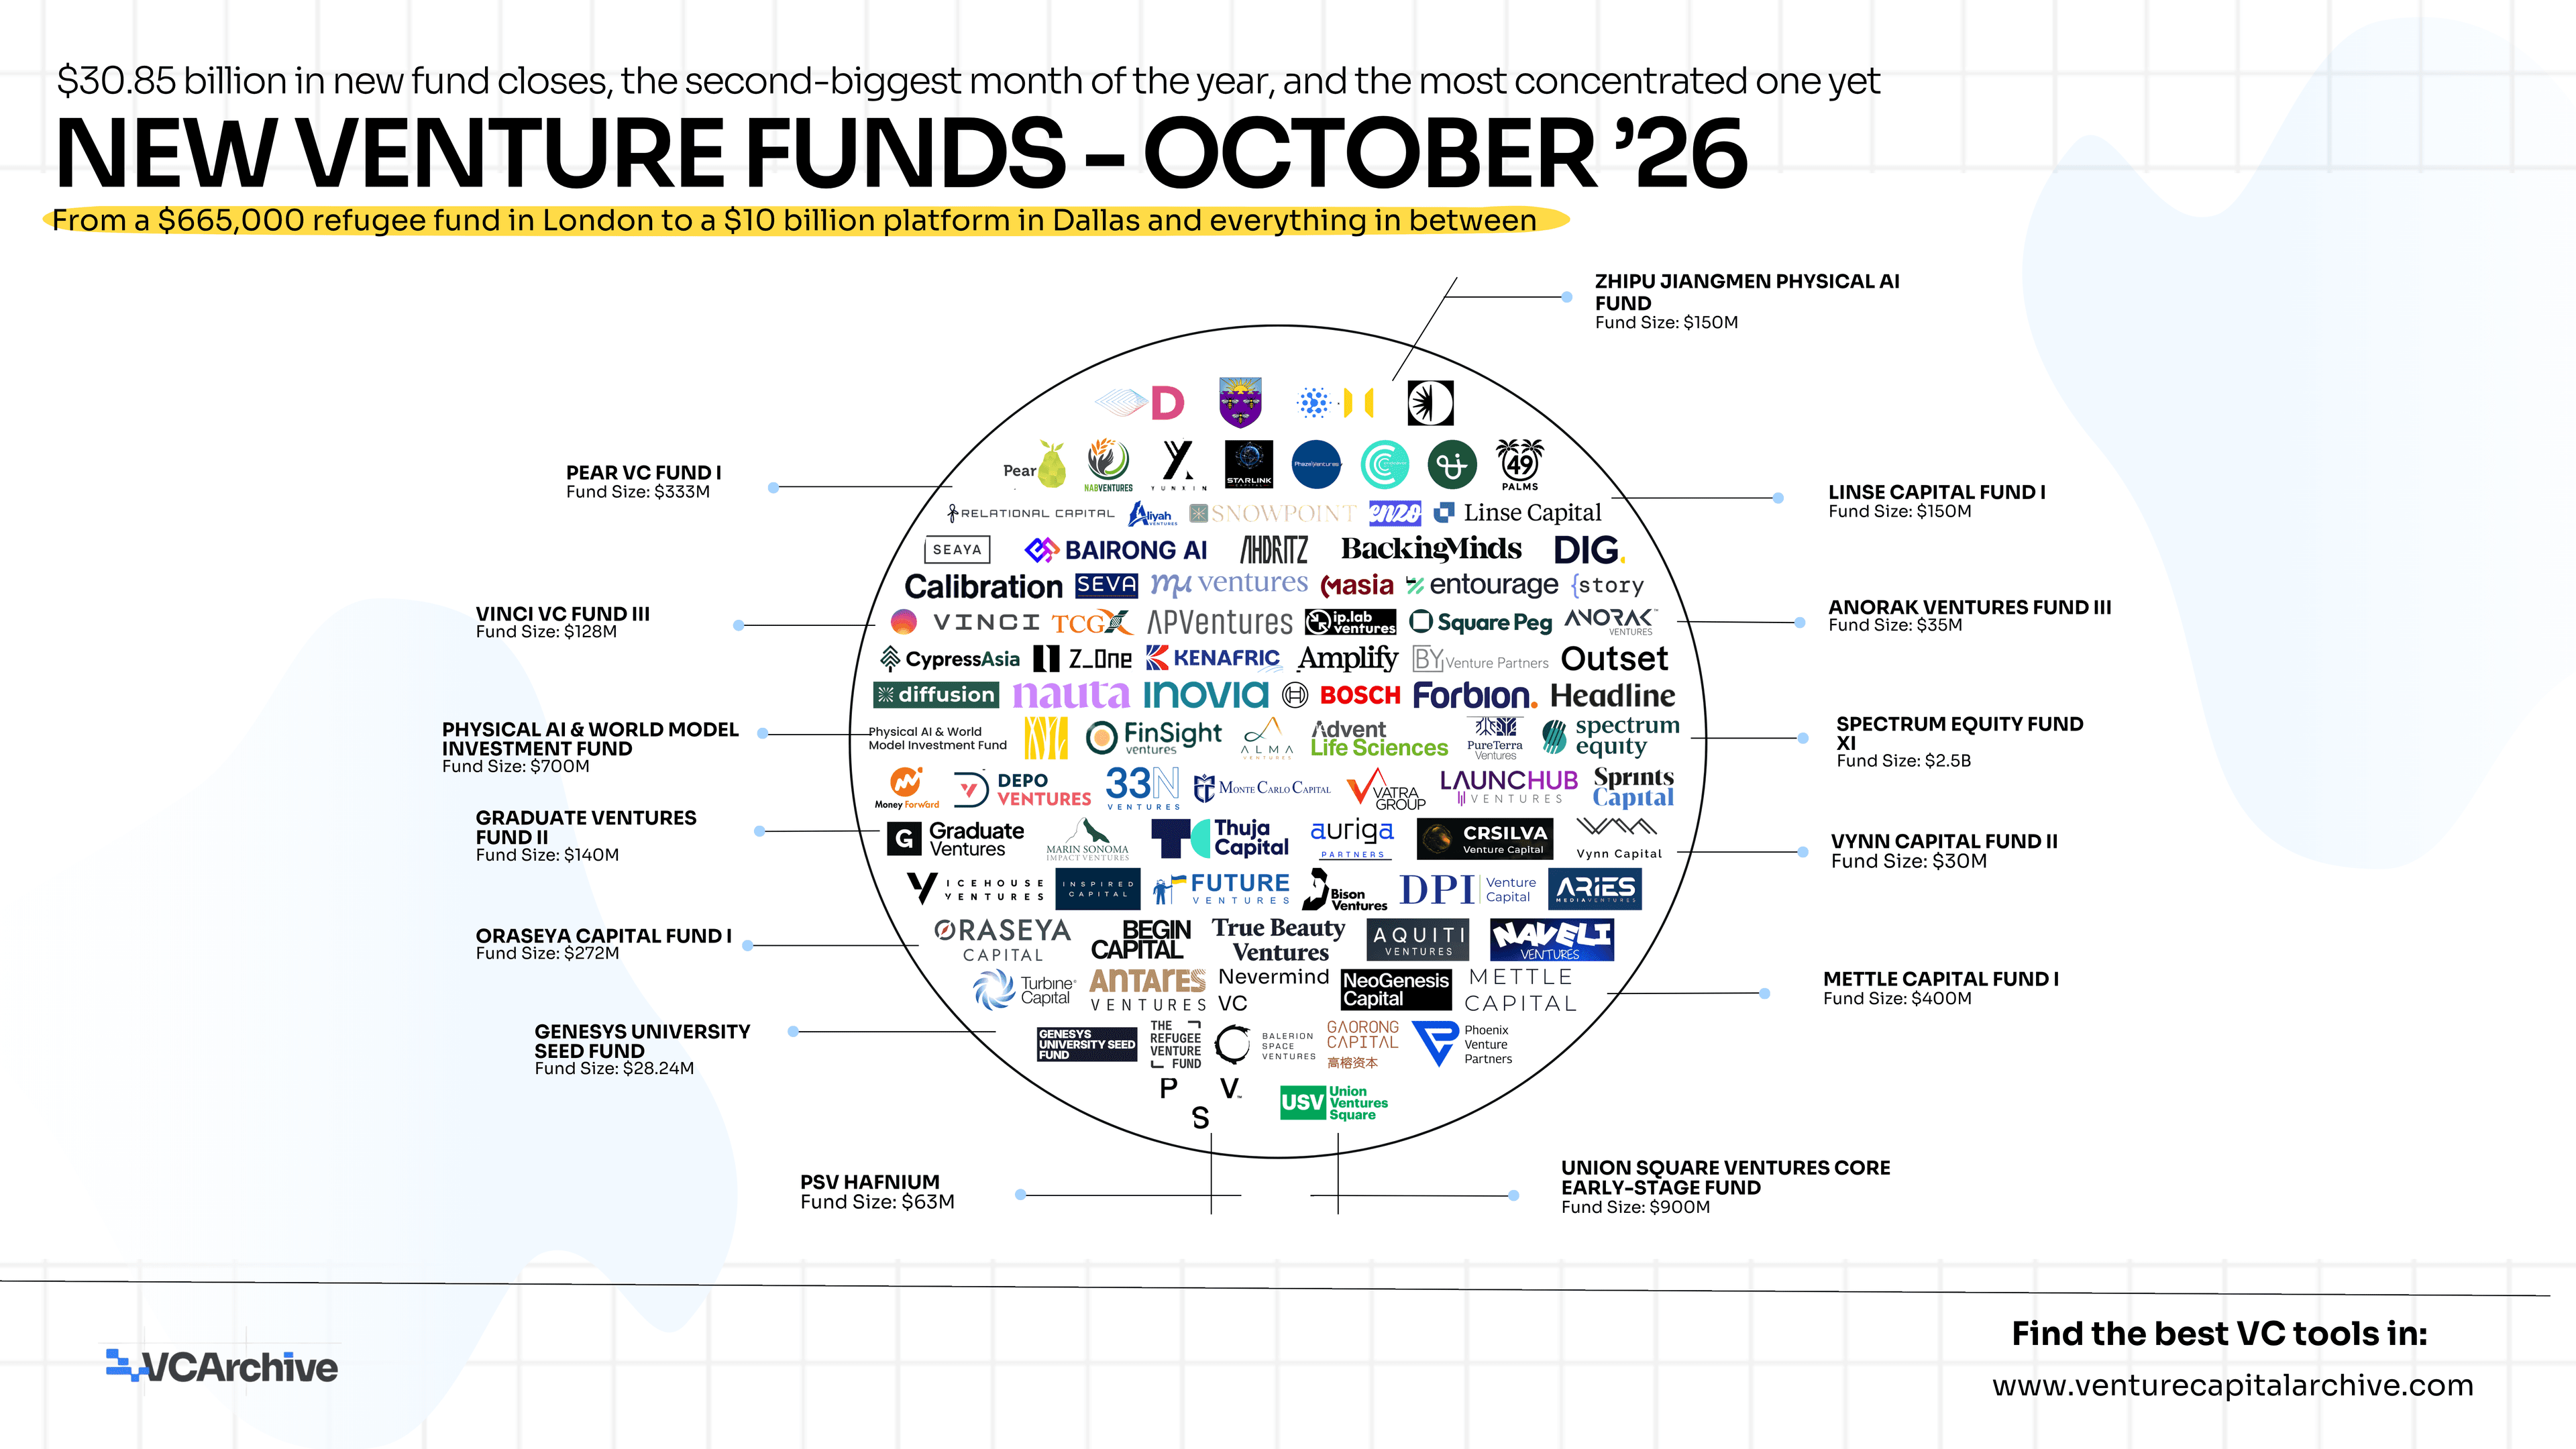
88 new venture capital funds closed in October 2026. Together, the 82 that disclosed their size committed $30.85 billion in fresh capital to the asset class. That is a large number for a single month, but the number alone misses the story. What matters is the shape of that capital where it concentrated, who it came from, and what that says about the state of venture in 2026.
One Fund. One Third of Everything.
Disruptive, the Austin and Dallas-based firm, closed its latest vehicle at $10 billion. That is 32% of all disclosed capital from the entire month. Take Disruptive out of October, and the remaining 87 funds raised a combined $20.85 billion. The concentration at the top of this month’s list is not an outlier, it is a pattern that has been building all year.
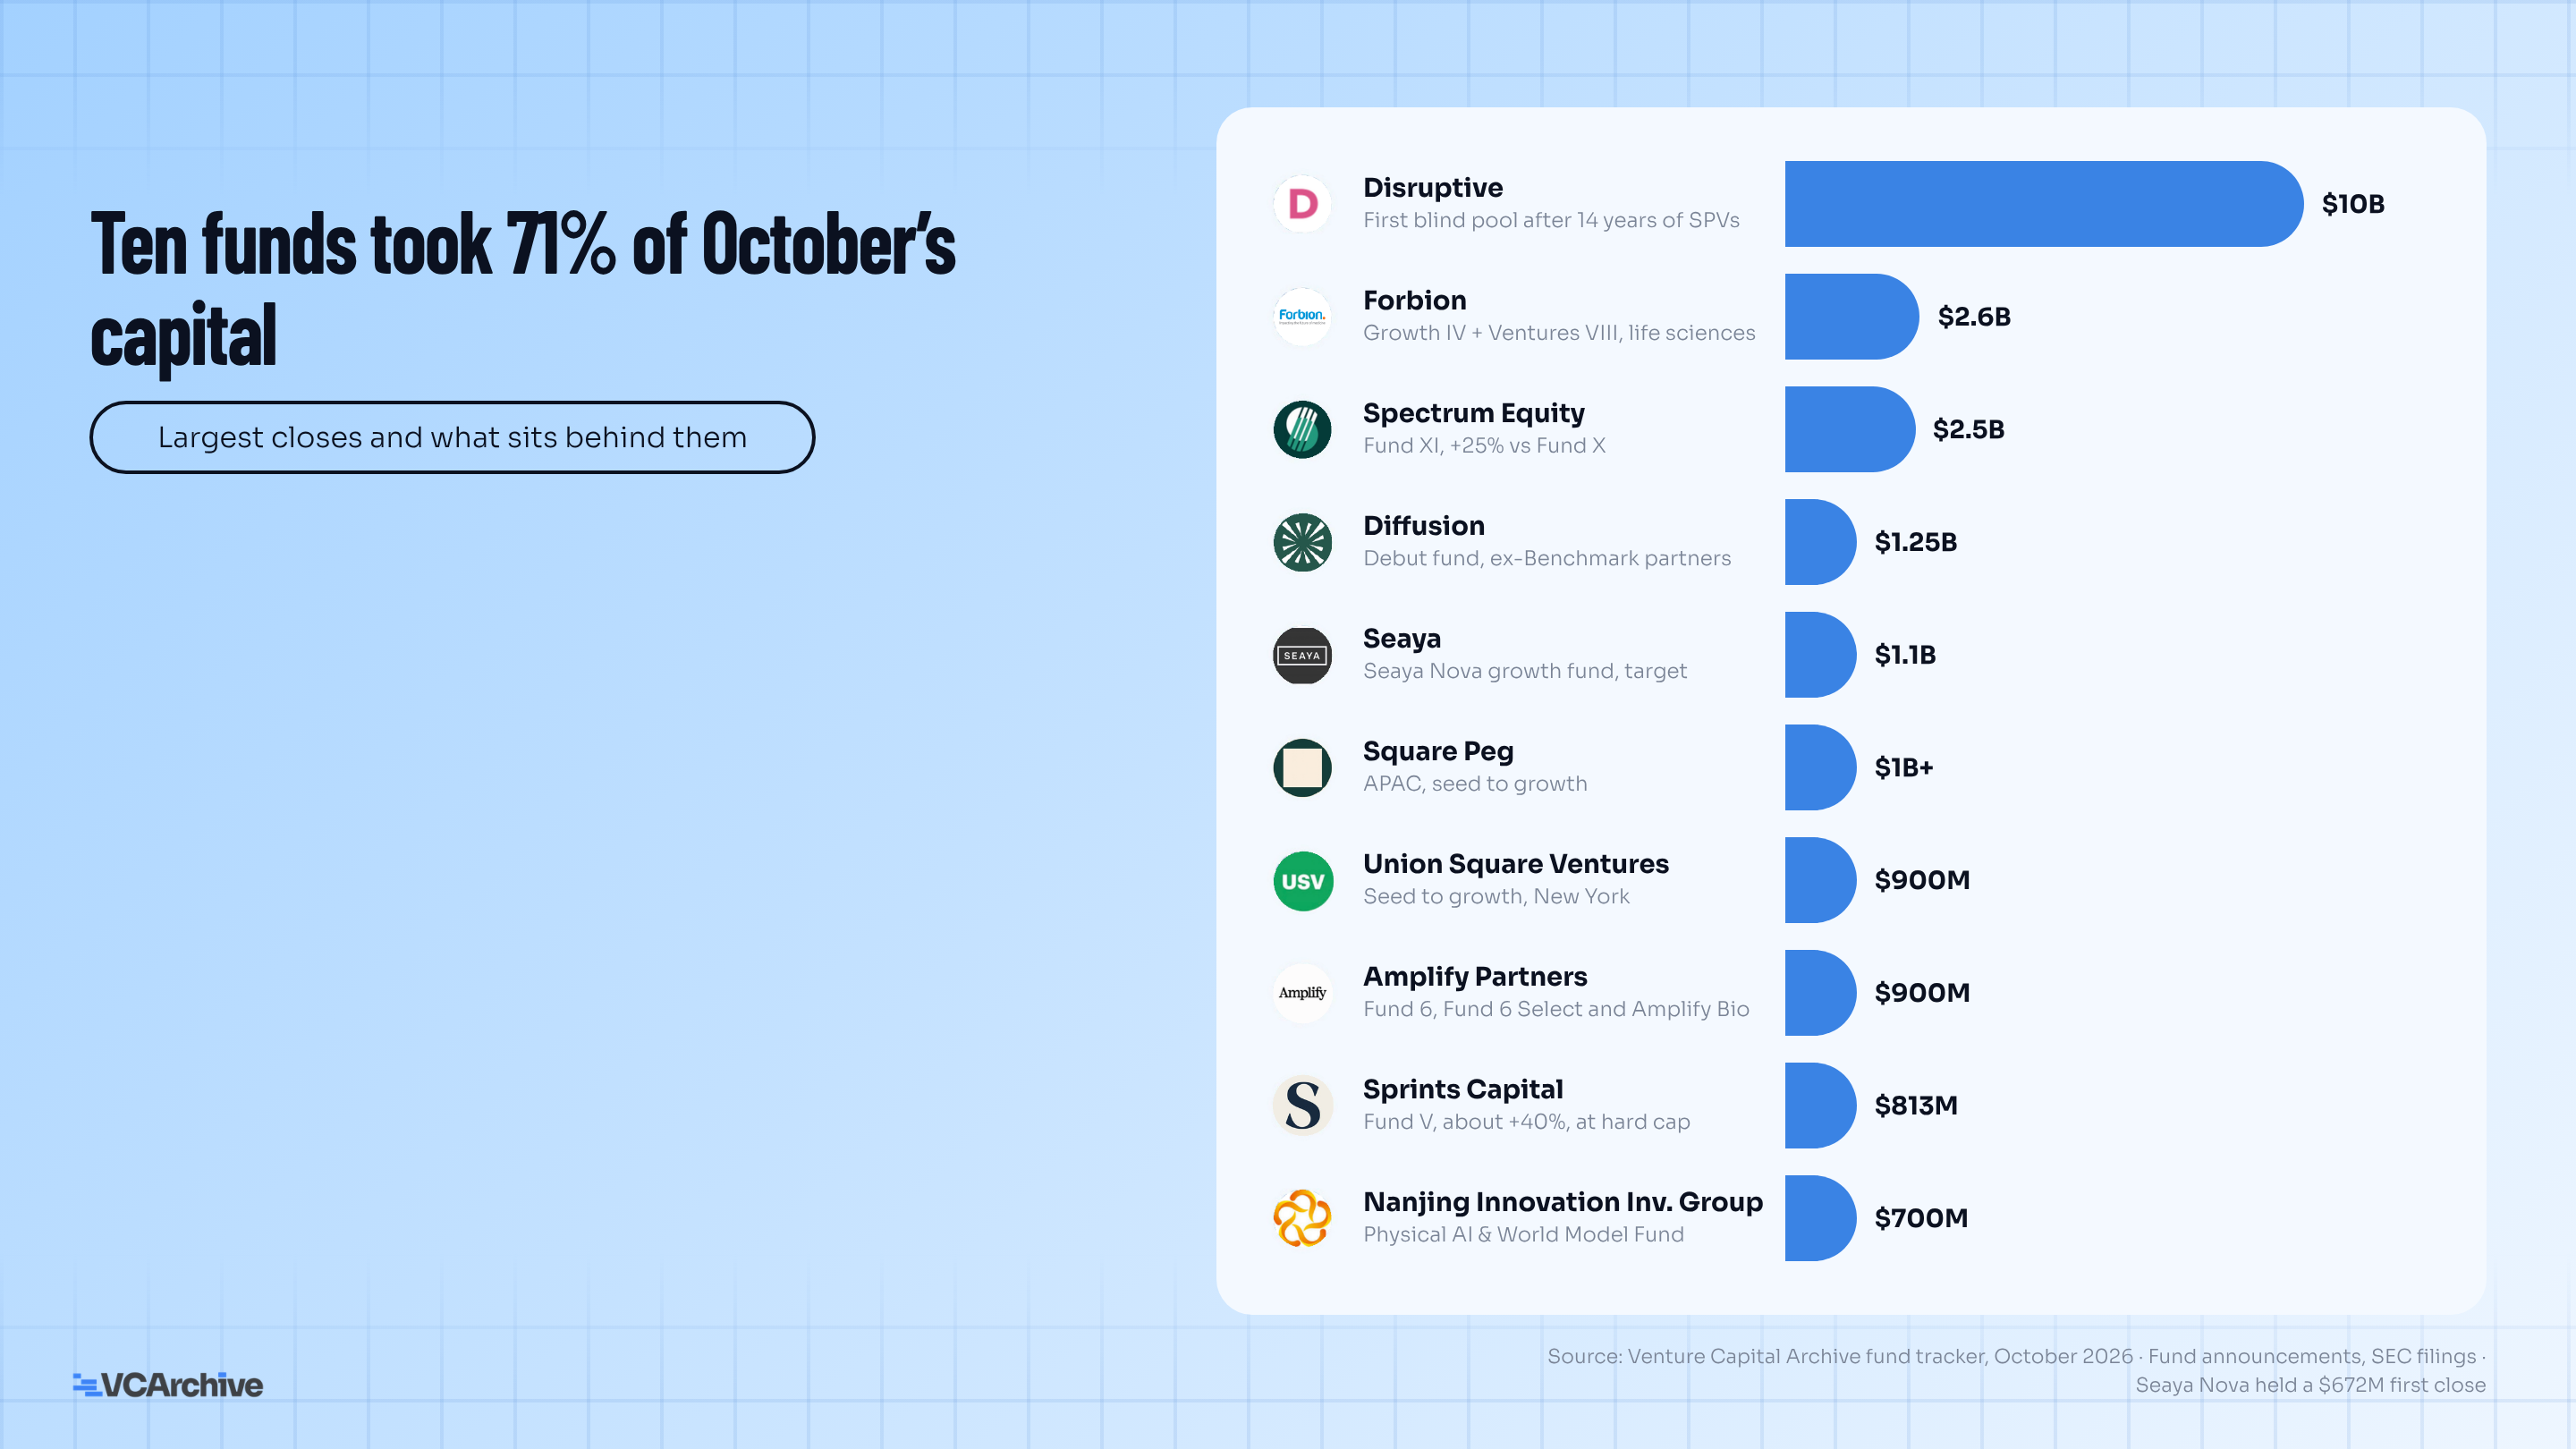
This dynamic runs well beyond October. PitchBook data through Q3 2026 shows just 6% of US funds, those at $500M or more capturing 78.1% of all capital raised this year. First-time fund closings are on pace for their lowest count in a decade. Liquidity is the engine behind this: LPs can only redeploy when old funds return capital, and with just 18 IPOs in Q3 2026, most are recycling commitments back to managers who have already distributed. Andreessen Horowitz alone closed $23.8 billion across multiple vehicles this year.
The Geography Is Getting Interesting
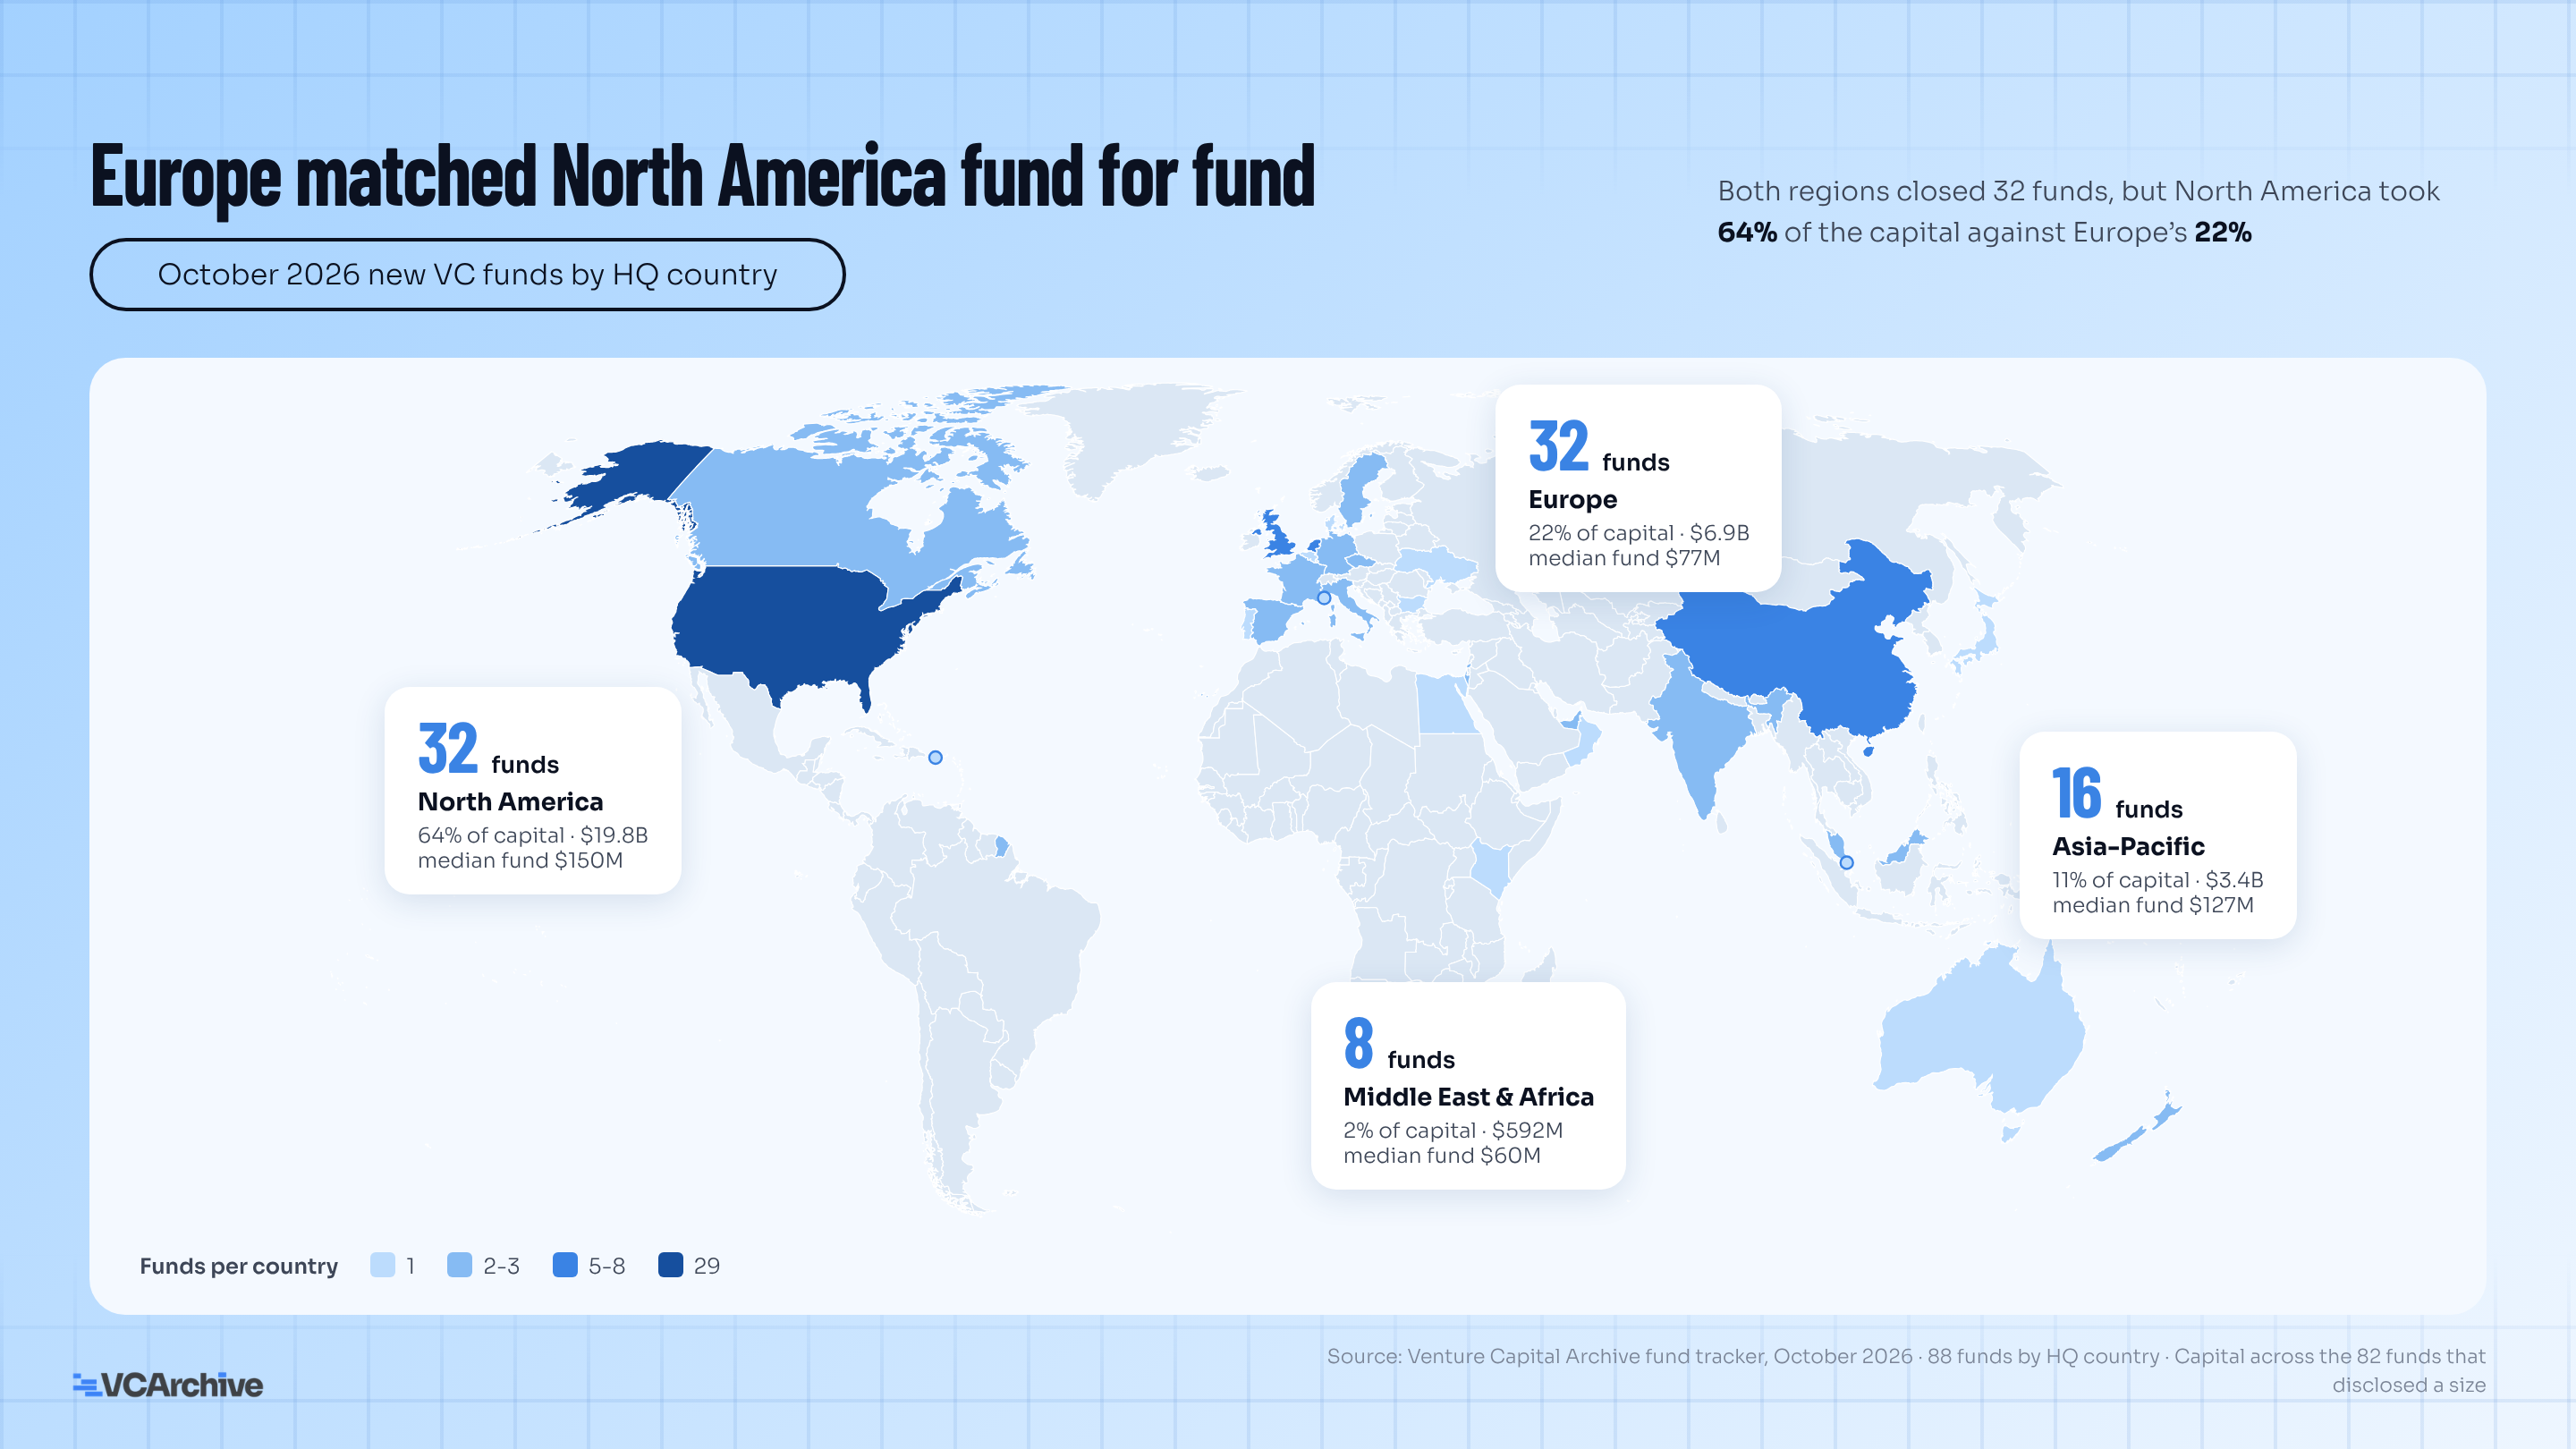
Zoom out from the capital totals and October’s list reads as a genuinely global snapshot. 32 funds closed in Europe, 32 in North America - equal in count, but the North American median was $150M versus $77M in Europe. Same number of funds, very different scale.
Standouts worth naming:
Seaya VC’s $1.1 billion close out of Barcelona is one of the largest Spanish venture vehicles in history. Diffusion raised $1.25 billion as its debut fund, led by ex-Benchmark partners. 33N Ventures ($223M, Porto) is one of the clearest signals yet that defence and cybersecurity have become a core thesis in European VC, not a niche. Vatra Group closed a $50 million fund investing from Kyiv. The Refugee Venture Fund closed at $665,000 - the smallest fund of the month by a wide margin, and worth naming alongside the $10 billion close because both happened in October 2026.
New fund activity also logged in Oman, Egypt, Kenya, Malaysia, New Zealand, Monaco, and Puerto Rico. The number of countries represented in a single month’s list keeps growing.
Physical AI Is Getting Its Own Capital
October was notable for how explicitly the physical AI thesis showed up in fund mandates, not as a background assumption but as the named focus.
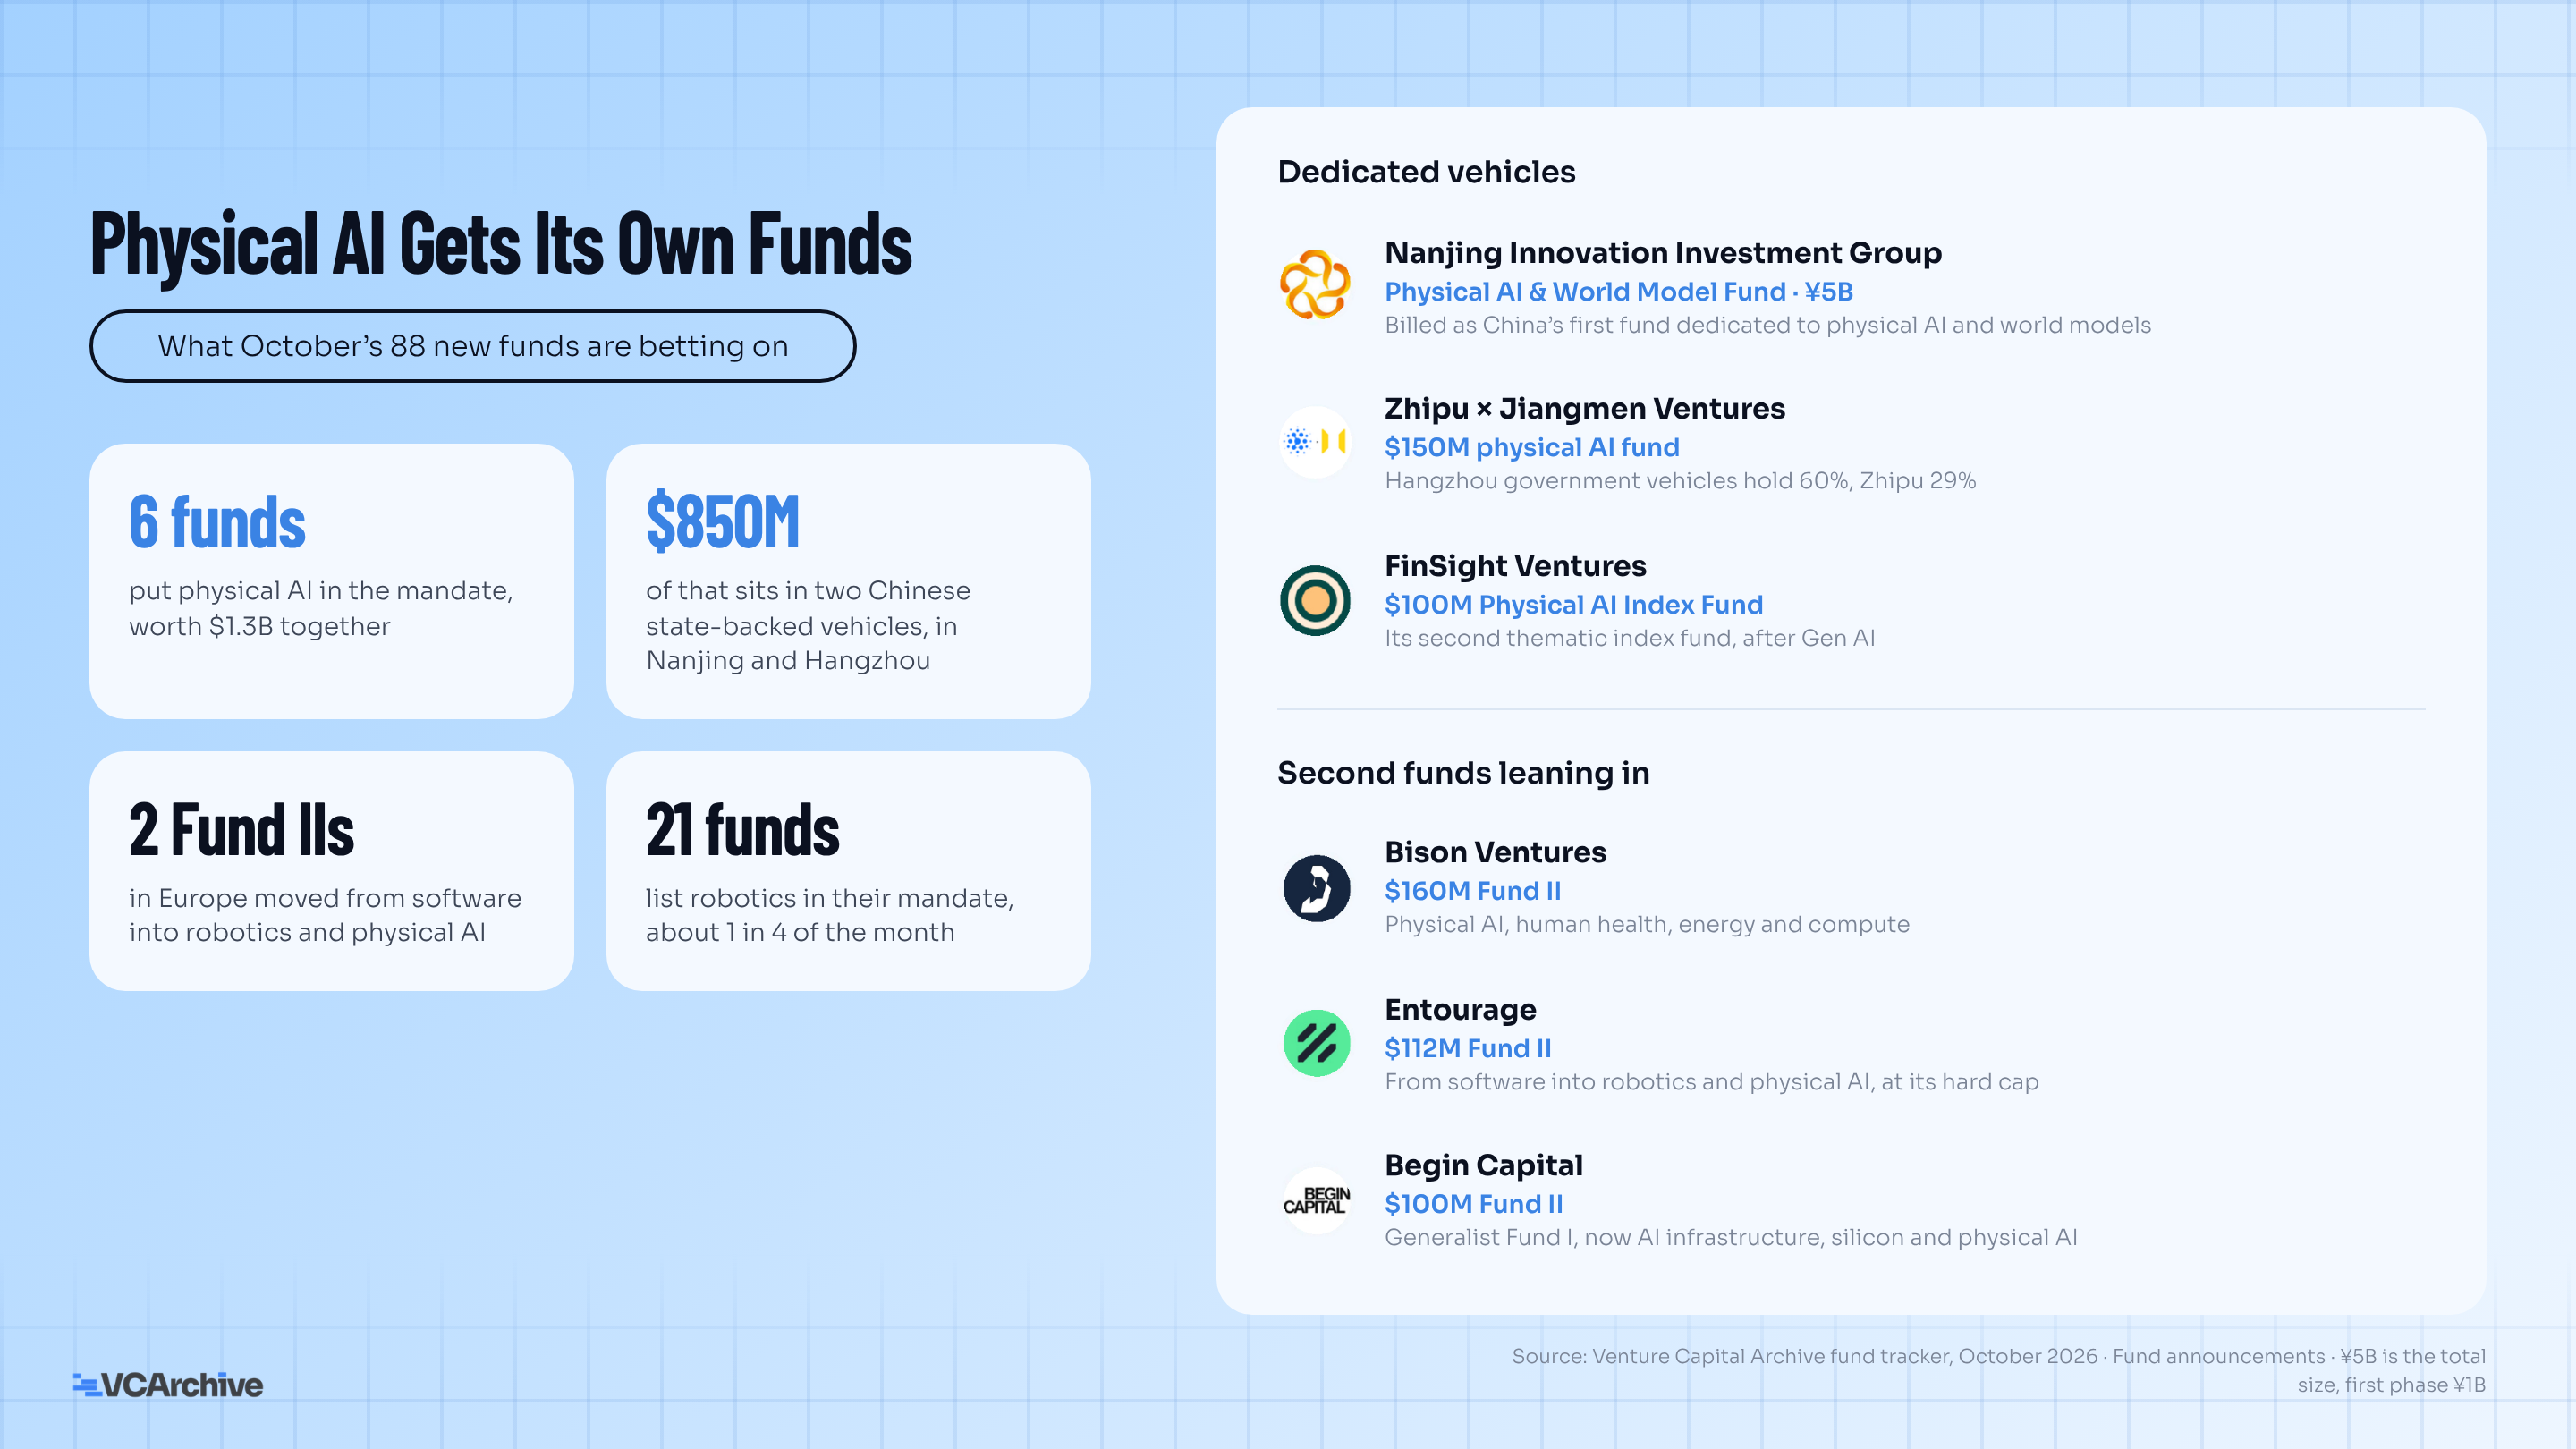 The global context behind this: robotics VC raised $18.8 billion in H1 2026 alone, already above the full-year 2025 total. China’s state-backed venture commitment to AI and robotics stands at $138 billion. 2 European Fund IIs in October explicitly pivoted their mandate from software into physical AI, a shift that would have been unusual two years ago and is now a fundraising story that LPs are receptive to.
Second Funds Grew Fastest
The top 3 step-ups in October were all Fund IIs. Entourage II up 261%, Enzo Ventures II up 100%, Marin Sonoma Impact II up 67%. The pattern held further down the list too: managers who proved their thesis on a first vehicle are getting rewarded with meaningful step-ups. The outlier was AP Ventures III, down 5% at $300M for its hydrogen and industrial tech mandate.
What This Month Suggests
Concentration will keep compounding
LP behavior right now is structural, not cyclical. Until the exit window reopens meaningfully, emerging and first-time managers will keep fighting for a diminishing share of available capital.
Physical AI has institutional backing
October had 6 funds with physical AI explicitly in the mandate, 21 with robotics somewhere in the thesis. That is about 1 in 4 of the month’s funds. The category has moved from thematic to core.
The mid-market is under pressure
39 funds under $100M shared 5.1% of October’s capital. Many of these are seed and pre-seed specialists. If this pressure persists, it will show up in startup formation rates 18 to 24 months from now.
Spain is becoming a European venture hub
Seaya’s $1.1B close plus 2 other Barcelona-area funds in a single month is not random. The ecosystem there has been building for a decade and October made it hard to ignore.
Geographic diversification is real, even if the capital is not there yet
The list of countries represented keeps expanding. The share of capital those funds hold is still small. That gap will close, slowly.
The Full List
The complete October 2026 New VC Funds list, all 88 funds, geographies, focus areas, disclosed sizes, and contact details are available below.
New Venture Funds - October 2026


Rows per page
More from Dario Villena
View author profile
Which Exit Strategy Do VCs Prefer?
Most venture capitalists do not prefer any particular exit strategy. What they prefer is a strong company to have several options.
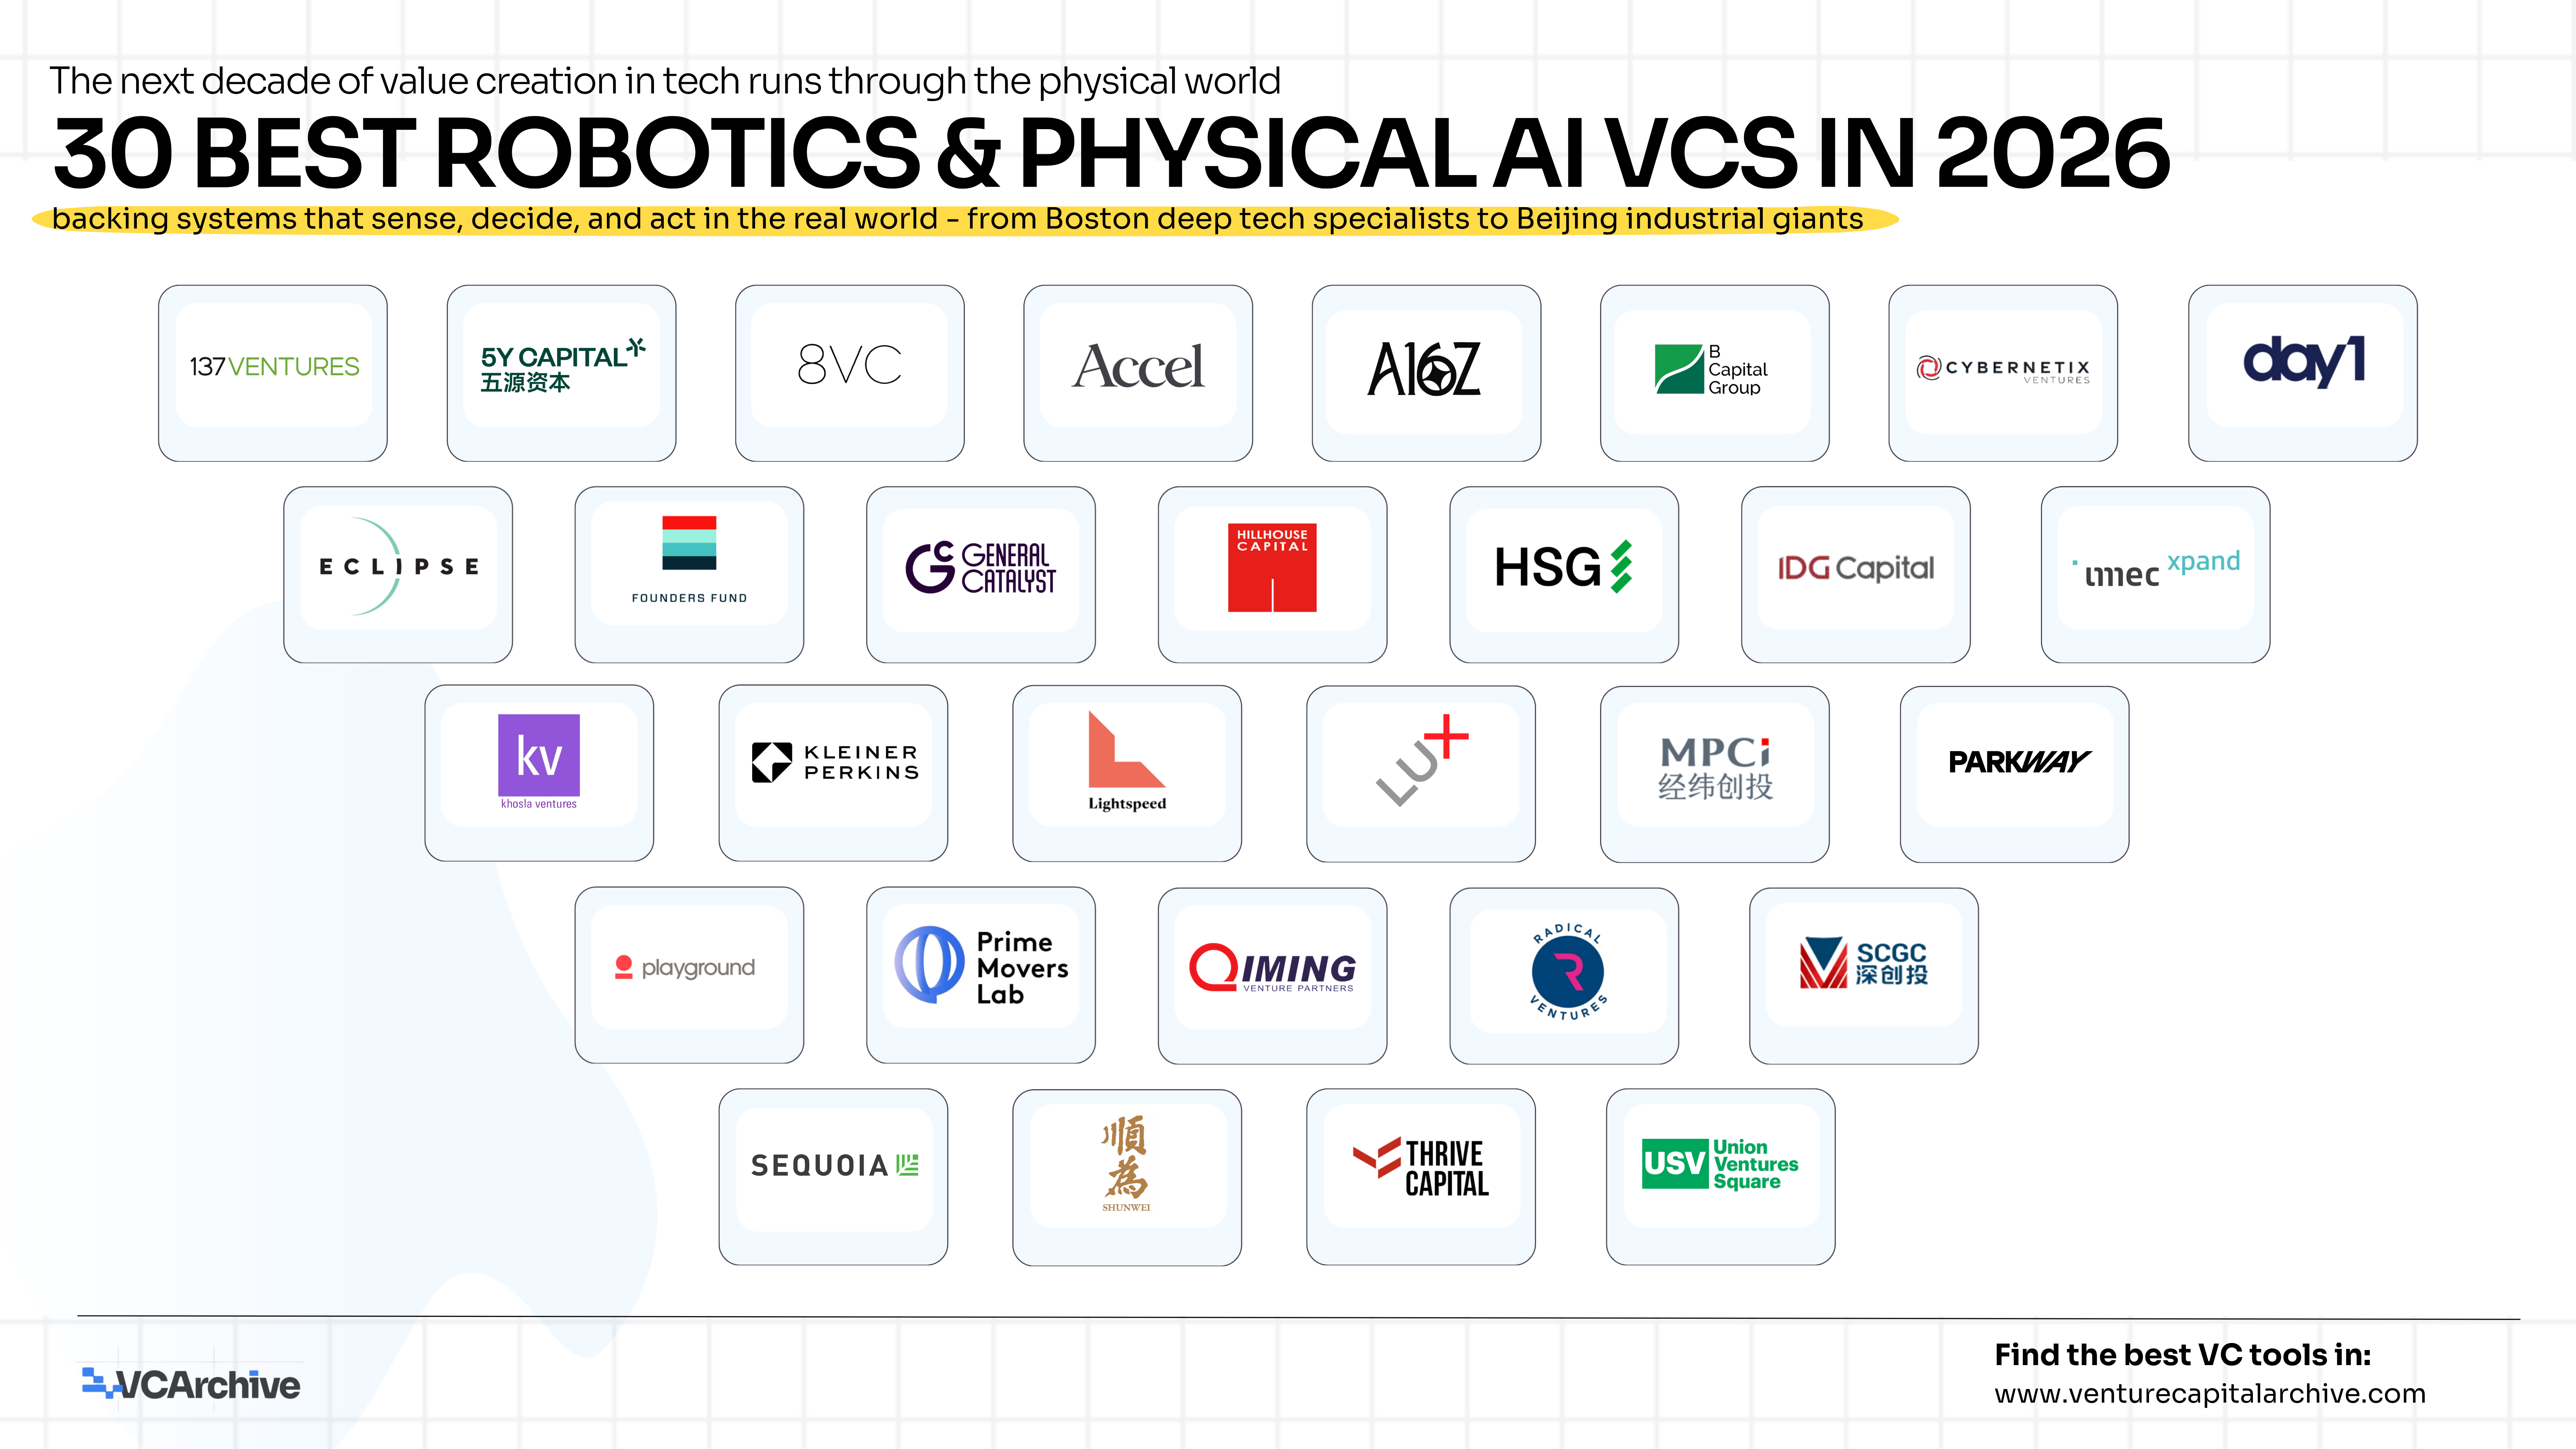
30 Best Active Robotics & Physical AI VCs in 2026
Software built the last decade. Physical AI is building the next one. These are the funds that are backing it.
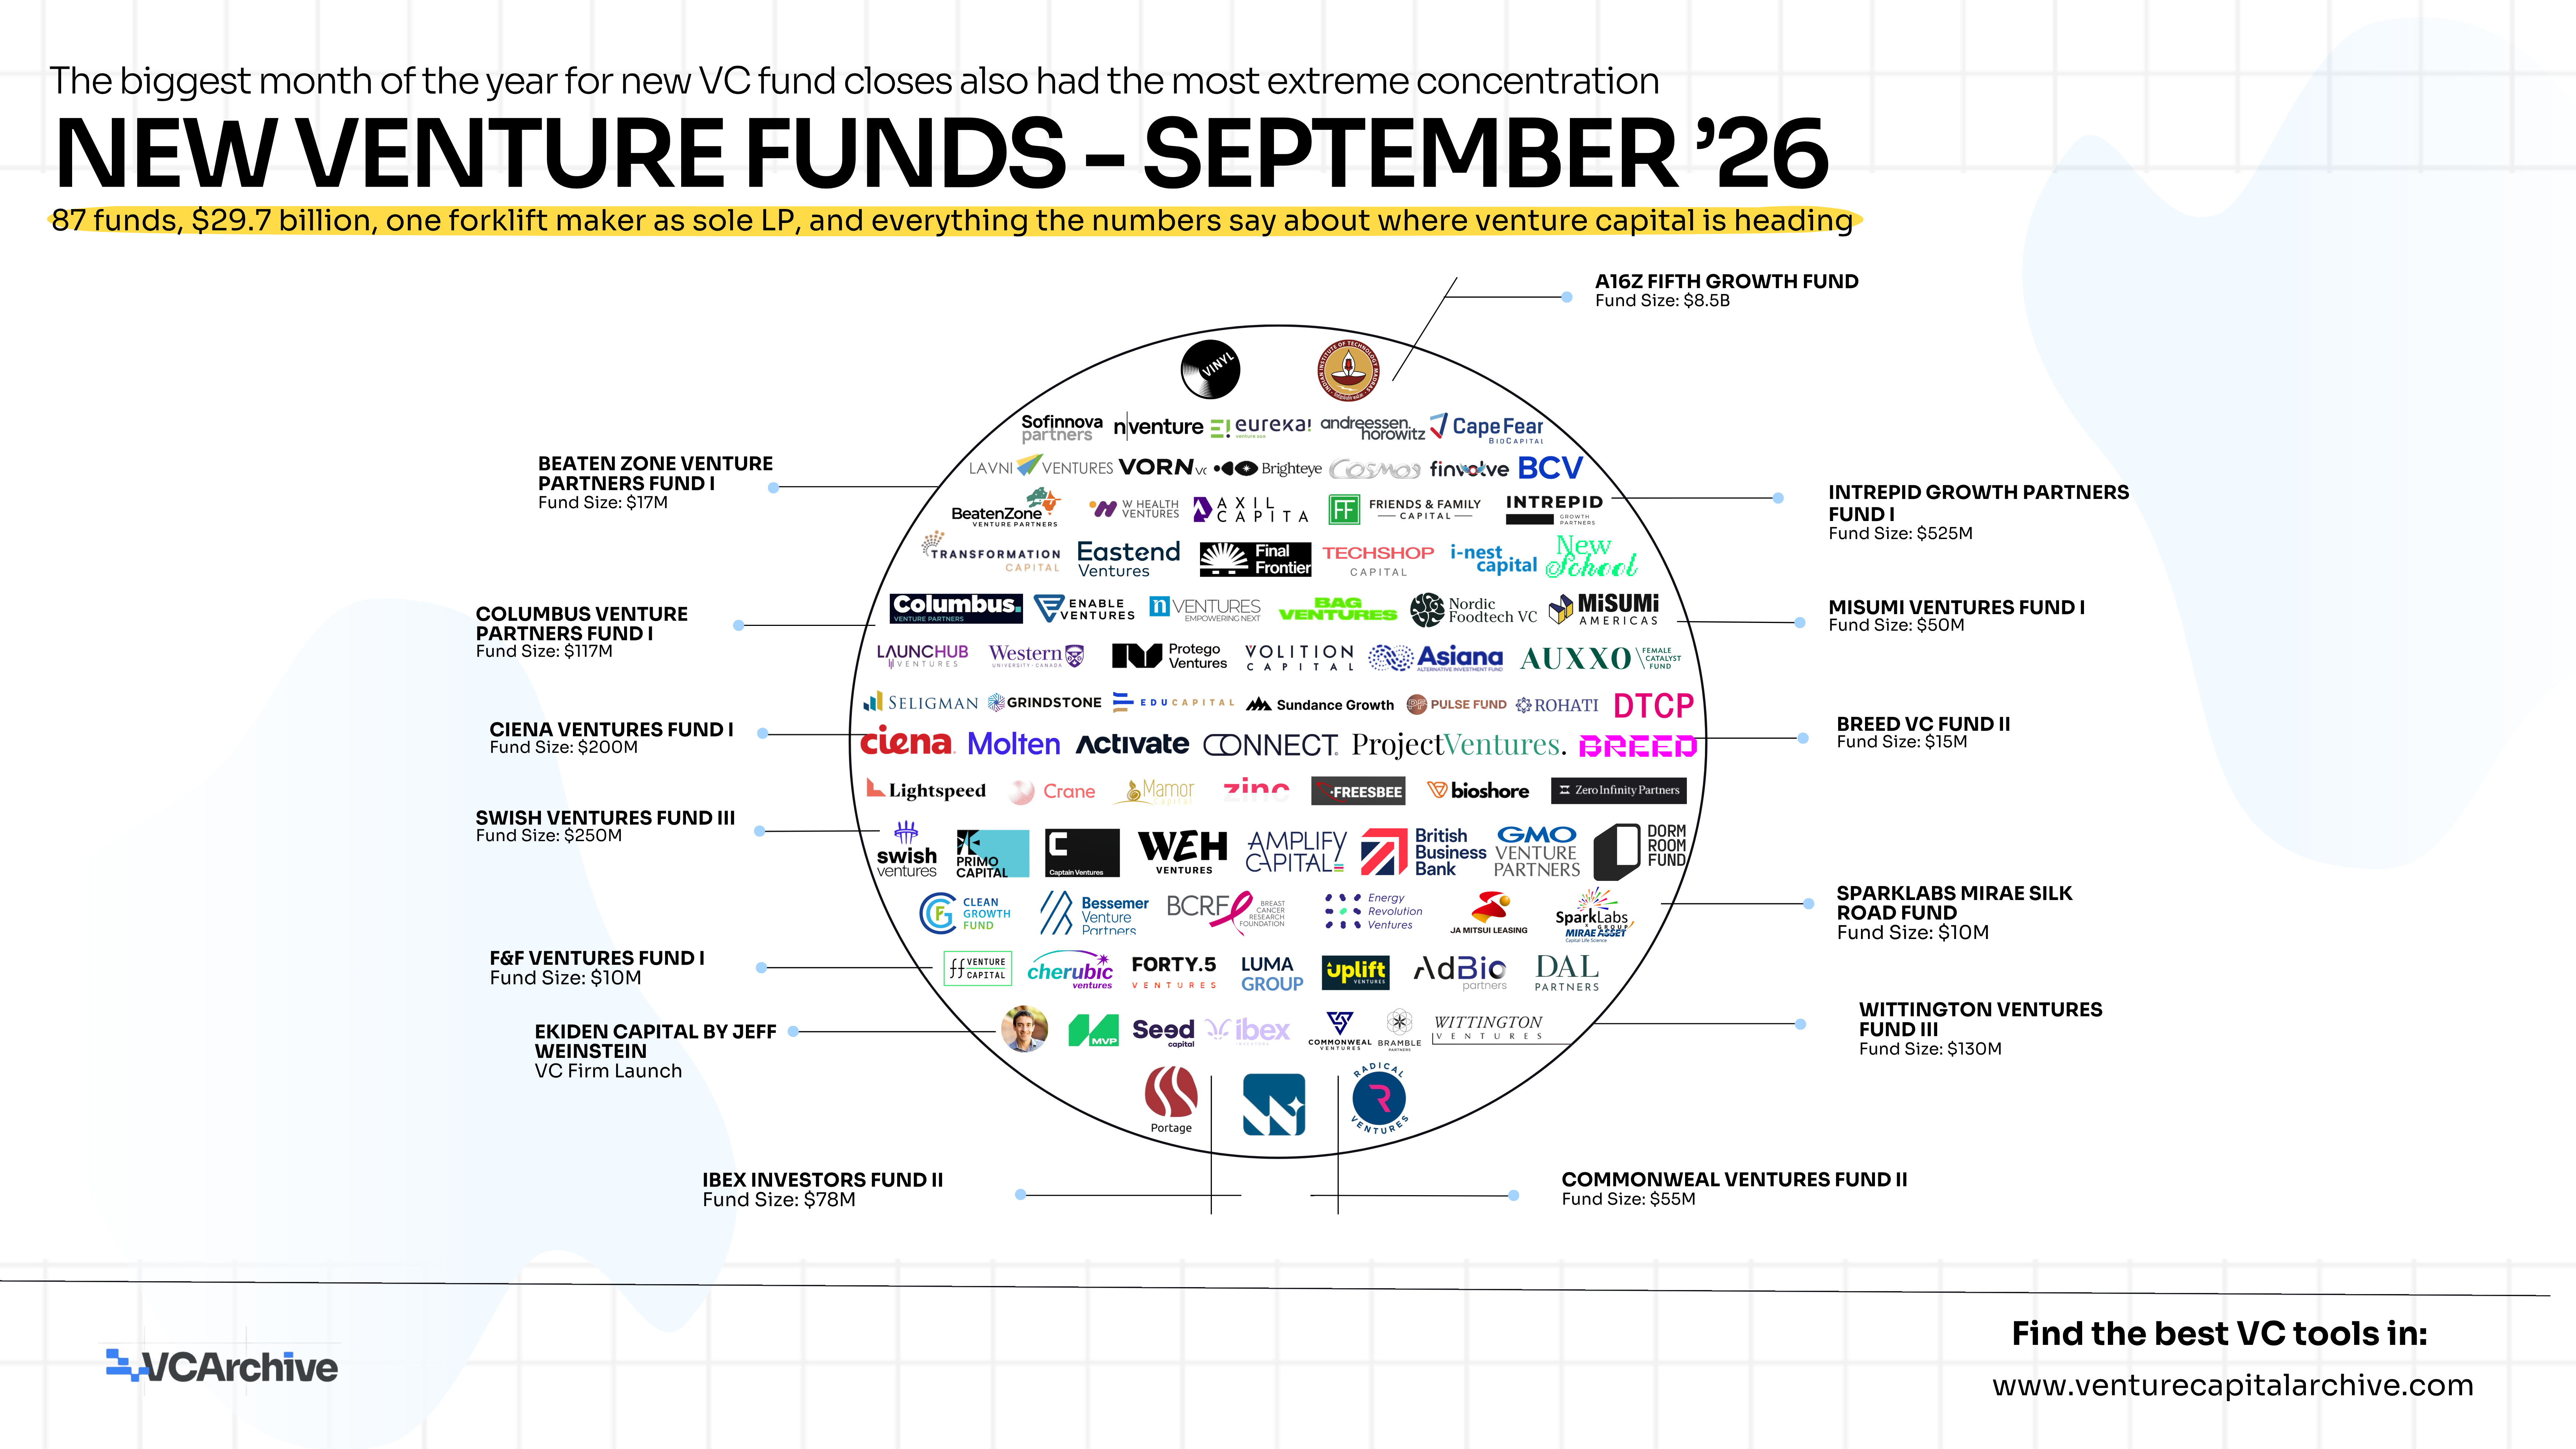
New Venture Funds - September 2026
The biggest fund formation month of 2026 also had the most extreme concentration we have tracked.